MicroStrategy Convertible Bond Model
A binomial valuation of Strategy’s (MicroStrategy’s) 0.625% convertible notes due 2028, using bitcoin as the state variable that drives both default risk and conversion value.
- Role
- Analyst
- Context
- Fall 2025 · FIN 330 Derivatives
- Team
- Individual model, built on the course’s binomial credit framework
- Deliverable
- Valuation model + brief
Summary
The question
Strategy funds bitcoin purchases with convertible debt, so the same asset drives the company’s solvency and the value of the conversion right. The question was what the 2028 notes were worth once default risk and the embedded options were valued together.
What I did
- Built a 12-step quarterly binomial tree for bitcoin (σ 47.7%, r 4.5%) from $92.67K and scaled it to the company’s 0.65M BTC to get an asset-value tree.
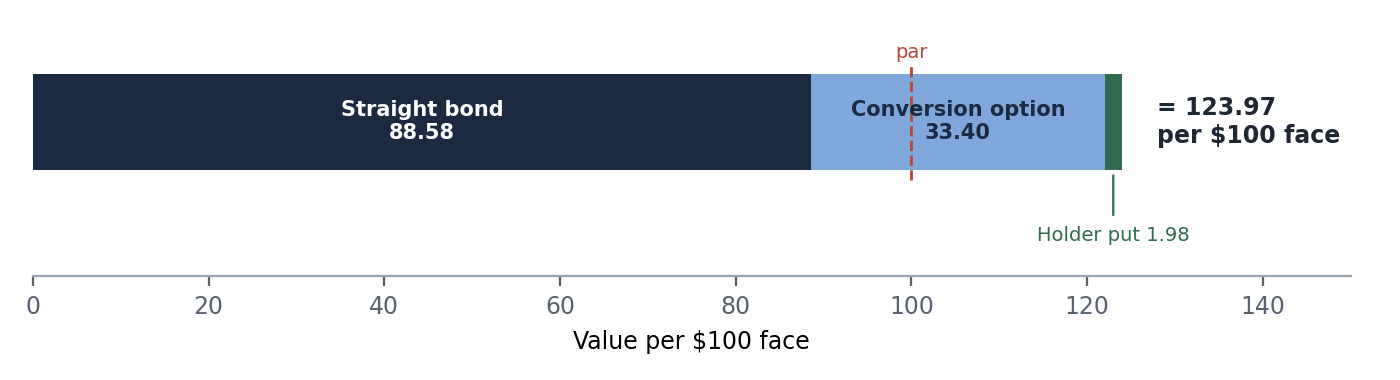
- Valued the straight bond through the tree with a $16B default boundary, then built equity and stock-price trees to value the conversion right at the $183.19 conversion price.
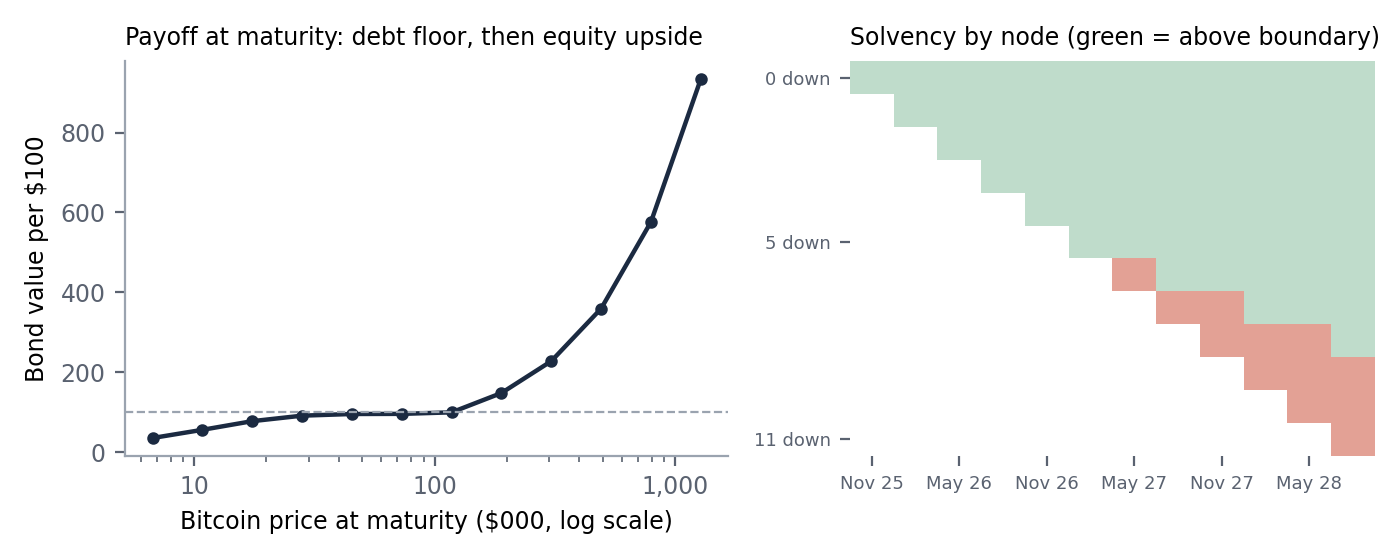
- Added the holder’s September 2027 put, summed the pieces, and mapped which nodes sit above the default boundary.
What it showed
For this issuer a single variable, bitcoin, moves credit risk and equity upside together. A bitcoin rally raises the option and cuts default risk at once; a sell-off hits both, which a one-factor tree captures directly.
From the work
Most convertibles combine a fairly stable credit with an equity option. Here the same variable, bitcoin, drives both the default risk and the conversion value. A bitcoin rally raises the option and lowers credit risk together; a sell-off hits both at once.
Valuation brief
Charts and slides
| Input | Value |
|---|---|
| Bitcoin price at valuation (Nov 23, 2025) | $92.67K |
| Bitcoin volatility | 47.7% |
| Risk-free rate | 4.5% |
| Time step | Quarterly, 12 steps |
| Bitcoin held | 0.65M BTC |
| Default boundary | $16B |
| Coupon / conversion price | 0.625% / $183.19 |
In my words
I completed this project in my derivatives class, valuing a MicroStrategy convertible bond with a focus on the conversion feature. Because MSTR's economics were dominated by its large bitcoin holding and limited operating cash flow, the project was an interesting way to connect bitcoin exposure, credit risk, and option value in one security.
Documents
If the preview does not load on your device, open the PDF in a new tab.
- Convertible valuation briefPDF · 2 pages · Excel model available
Coursework model built on the FIN 330 binomial framework. Note terms come from Strategy’s public debt disclosure (Dec 2, 2025). Not investment advice.